Tax Help Jul 29, 2026

Understanding IRS Tax Return Transcripts: A Complete Guide

Understanding IRS Tax Return Transcripts: A Complete Guide
Understanding IRS tax return documents and how to manage your finances effectively.

A transcript of your IRS tax return is essential if you need to check your financial records or confirm details with the IRS. Although it differs from your actual tax return, it is significant in many cases. We will discuss what a tax return transcript is, when you might require one, and how to obtain one in this tutorial.

A transcript of your IRS tax return is a synopsis of your tax return, including most of the line items from your first filing. It does not, however, incorporate modifications made after the return was filed. Although it isn’t a replica of your tax return, it still has enough information to be helpful for several uses. Lenders and other institutions often require this document to validate your income and tax status when you apply for loans, mortgages, or financial aid.

Types of IRS Transcripts

There are several types of IRS transcripts, each serving a different purpose:

  1. Tax Return Transcript: A summary of your original tax return (Form 1040, 1040A, or 1040EZ). This is typically used for income verification for mortgage applications or student loans.
  2. Tax Account Transcript: Provides primary data such as return type, marital status, and taxable income. It also includes any adjustments made after filing.
  3. Record of Account Transcript: Combines the tax return and tax account transcripts. It’s helpful if you need a more detailed overview of your tax account.
  4. Wage and Income Transcript: This shows W-2s, 1099s, and 1098s data. It’s helpful if you need a breakdown of income and tax details that employers have submitted to the IRS.
  5. Verification of Non-Filing Letter: For those who didn’t file a tax return, this document proves to third parties that you didn’t file for a specific tax year.

Why You Might Need a Tax Return Transcript

There are various circumstances in which a transcript of your tax return may be required. For instance, this document is frequently needed by lenders and other financial organizations when you apply for a school loan or a mortgage. Tax professionals may also submit modifications or request them to address inconsistencies. You must still prove your income for a government program or obtain your original tax return. In that scenario, the quickest and most straightforward method to get this data is through an IRS tax return transcript.

How to Get an IRS Tax Return Transcript

It is simple to request a transcript of your IRS tax return. You can view or download your transcript online using the IRS’s “Get Transcript” function. Alternatively, you can mail in a request using IRS Form 4506-T, but the processing time will be longer. Transcripts are typically only available for the last three years, so it’s better to seek them as soon as possible if you require earlier information.

Conclusion

An IRS tax return transcript is required when confirming tax information or submitting a loan application. Although it isn’t a full copy of the tax return, it has enough information to satisfy most legal and financial requirements. You can be ready for any circumstance that calls for documentation of your financial history by being aware of how to access and utilize this resource.
Share this article:

Insights in Your Inbox

Join tax professionals getting practical resolution strategy, IRS updates,
and practice-scaling playbooks - about twice a month.

This field is for validation purposes and should be left unchanged.
Tax News Jul 28, 2026

How Energy-Efficient Home Improvements Can Reduce Your Energy Bills and Taxes

How Energy-Efficient Home Improvements Can Reduce Your Energy Bills and Taxes
Energy saving concept and financial savings. A LED lamp on top of money banknotes seen on a rustic wooden table. Us One dollar bills.

Energy efficiency isn’t just a buzzword; it’s a smart financial strategy that benefits both homeowners and the environment. By making energy-efficient home improvements, you can significantly reduce your energy bills and qualify for valuable tax credits. In this blog, we’ll explore how energy-efficient upgrades can save you money, the specific tax credits available, and how to claim them. Let’s dive into the world of energy efficiency and discover how these improvements can benefit your home and wallet.

The Importance of Energy-Efficient Home Improvements

Home energy efficiency is crucial for several reasons:

  1. Reduced Energy Bills: Energy-efficient upgrades can lower your energy consumption, leading to substantial savings on your utility bills.
  2. Environmental Impact: Reducing energy usage helps decrease greenhouse gas emissions, contributing to a healthier planet.
  3. Increased Home Value: Energy-efficient homes often have higher resale values and are more attractive to potential buyers.
  4. Comfort and Health: Upgrading your home’s energy systems can improve indoor air quality and overall comfort.

Tax Credits for Energy-Efficient Improvements

The IRS offers two significant tax credits to encourage homeowners to invest in energy-efficient improvements: the Energy Efficient Home Improvement Credit and the Residential Clean Energy Credit.

1. Energy Efficient Home Improvement Credit

This credit is designed for homeowners who make energy-efficient improvements, additions, or renovations to an existing home. Unfortunately, it does not apply to newly constructed homes. Eligible expenses include:

  • Exterior Doors, Windows, and Skylights: Upgrading to energy-efficient models can reduce drafts and improve insulation.
  • Insulation Materials: Proper insulation helps maintain indoor temperatures, reducing the need for heating and cooling.
  • Central Air Conditioners, Water Heaters, Furnaces, Boilers, and Heat Pumps: Modern, energy-efficient systems consume less energy, leading to lower utility bills.
  • Biomass Stoves and Boilers: These eco-friendly heating options have their own separate annual credit limit.
  • Home Energy Audits: Professional evaluations can identify areas for improvement and potential savings.

Credit Amount:

  • 2023 through 2032: 30% of the total improvement expenses, up to a maximum of $1,200 annually.
  • Biomass Stoves and Boilers: Up to $2,000 annually with no lifetime limit.

2. Residential Clean Energy Credit

This credit applies to both existing homes and newly constructed homes. It covers the installation of renewable energy systems, including:

  • Solar, Wind, and Geothermal Power Generation Equipment: Harness renewable energy to power your home.
  • Solar Water Heaters: Use solar energy to heat your water efficiently.
  • Fuel Cells and Battery Storage: Innovative energy storage solutions that complement renewable energy systems.

Credit Amount:

  • 2022 – 2032: 30% of the total improvement expenses, with no annual maximum or lifetime limit.
  • 2033: 26%, no annual maximum or lifetime limit.
  • 2034: 22%, no annual maximum or lifetime limit.

Who Can Claim These Credits?

Homeowners who make qualifying energy-efficient improvements to their principal or, in some cases, secondary residences can claim these credits. Renters may also be eligible for specific costs, though landlords cannot claim these credits for improvements made to rental properties. For detailed eligibility criteria, refer to the instructions for IRS Form 5695.

How to Claim the Credits

To claim the Energy Efficient Home Improvement Credit or the Residential Clean Energy Credit, taxpayers should:

  1. Complete Form 5695: This form, titled “Residential Energy Credits,” is used to calculate and claim your credits.
  2. File with Your Tax Return: Attach Form 5695 to your annual tax return when you file.

Practical Tips for Homeowners

To maximize your savings and ensure you qualify for the available credits, consider the following tips:

  • Plan Your Upgrades: Prioritize improvements that offer the highest energy savings and return on investment.
  • Hire Qualified Professionals: Ensure that installations and upgrades are performed by licensed and experienced contractors.
  • Keep Records: Maintain detailed records of all expenses and improvements, including receipts and contractor invoices.
  • Stay Informed: Tax laws and credits can change, so stay updated on the latest information from the IRS.

Beware of Scams

As energy-efficient upgrades become more popular, so do scams. Be cautious of companies that make exaggerated claims about the benefits of their products or services. Always verify the credentials of contractors and consult multiple sources before making decisions.

Real-Life Success Stories

To illustrate the impact of energy-efficient home improvements, let’s look at a few real-life success stories:

  • The Smith Family: By replacing their old windows with energy-efficient models and installing a new central air conditioning system, the Smiths reduced their annual energy bills by 20%. They also claimed the Energy Efficient Home Improvement Credit, which covered a significant portion of their costs.
  • Green Solutions, Inc.: A homeowner in California installed a solar power system and battery storage, allowing them to generate and store their own energy. This not only reduced their reliance on the grid but also qualified them for the Residential Clean Energy Credit, significantly offsetting the installation costs.
  • Eco-Friendly Upgrade: After a professional home energy audit, the Johnsons upgraded their insulation and installed a biomass stove. These improvements made their home more comfortable in winter and summer, and they claimed the maximum allowable credits for both upgrades.

Conclusion

Energy-efficient home improvements are a win-win for homeowners, offering both immediate savings on energy bills and long-term financial benefits through tax credits. By understanding the available credits and making strategic upgrades, you can enhance the comfort and value of your home while contributing to a sustainable future.

Don’t miss out on these valuable opportunities. Start planning your energy-efficient home improvements today, and enjoy the benefits of lower energy bills and generous tax credits. For more information, consult the IRS guidelines or speak with a tax professional.

References:

By investing in energy-efficient home improvements, you not only save money but also contribute to a greener planet. Embrace the change and reap the rewards today!

Share this article:

Insights in Your Inbox

Join tax professionals getting practical resolution strategy, IRS updates,
and practice-scaling playbooks - about twice a month.

This field is for validation purposes and should be left unchanged.
Tax Help Jul 27, 2026

Identity Theft in Tax Profession: Key Prevention Tips

Identity Theft in Tax Profession: Key Prevention Tips

In today’s digital age, tax professionals are increasingly becoming targets for identity thieves. The IRS and the Security Summit have launched a vital educational series to help tax pros recognize and respond to data theft threats. As part of the ongoing “Protect Your Clients; Protect Yourself” series, this article will delve into the critical warning signs of identity theft, preventive measures, and steps to take if a breach occurs.

Understanding the Threat: Identity Theft in the Tax Profession

Identity theft is a growing concern in the tax industry. Criminals are constantly evolving their tactics, and with the implementation of stronger fraud defenses by the IRS and the Security Summit partners, tax professionals have become prime targets. These thieves aim to gain access to valuable client information to prepare fraudulent tax returns, exploiting the information to their advantage.

IRS Commissioner Danny Werfel emphasizes the importance of vigilance, stating, “Identity thieves are creative, and they can find ways of quietly penetrating systems.” Many tax professionals have discovered breaches only after weeks or months, making it crucial to recognize the warning signs early to protect both their business and their clients.

Warning Signs of Identity Theft

Tax professionals must be aware of several warning signs, both from their clients and within their own systems. Identifying these signs promptly can help mitigate the damage and prevent further security issues.

Red Flags from Clients

  1. Unexpected IRS Online Account Notices: Clients might receive notifications about the creation of an IRS Online Account without their consent, or they might discover unauthorized access to their existing accounts. If clients notice that their IRS Online Account has been disabled or that they receive a tax transcript they didn’t request, these could be indicators of identity theft.
  2. Inaccurate IRS Notices: Clients might receive IRS notices that don’t match their tax filings, such as incorrect balance due notices. They may also receive refunds without having filed a tax return or be contacted by clients about calls or emails that the tax pro didn’t make.

Red Flags within the Tax Professional’s Business

  1. Unusual Computer Behavior: Slow or unresponsive computers, unexpected cursor movements, or unauthorized changes in data can be signs of a system compromise. Tax professionals should also be cautious if they are locked out of their network or if client tax returns are being rejected because their Social Security number has already been used.
  2. Suspicious IRS Communications: Receiving IRS authentication letters (5071C, 6331C, 4883C, 5747C) without having filed a tax return can indicate a breach. Similarly, getting more e-file receipt acknowledgments than the number of returns filed or seeing transcripts in the Secure Object Repository that weren’t ordered are red flags.
  3. CAF Number Compromises: Notifications from the IRS about a compromised Centralized Authorized File (CAF) number or a client that the tax professional doesn’t represent are also concerning. Proactively protecting the CAF number and possibly requesting a new one can help safeguard against misuse.

Steps to Take If a Data Breach Occurs

If a tax professional or their firm falls victim to a data breach, immediate action is crucial to minimize the impact. Here’s what to do:

  1. Report the Incident: Notify the local IRS Stakeholder Liaison immediately. They will coordinate with the appropriate IRS offices to block fraudulent returns and assist in managing the breach. Speed in reporting is essential to limit the damage.
  2. Contact State Tax Agencies: Visit the Federation of Tax Administrators to report the breach to the relevant state tax agency. They can provide additional support and guidance on managing the breach.
  3. Proactive Client Communication: Inform clients who may have been affected by the breach. Suggest steps such as obtaining an Identity Protection PIN or completing Form 14039, the Identity Theft Affidavit, to protect their personal information.

Preventive Measures and Resources

Tax professionals should take proactive steps to protect their systems and client data. Here are some key resources and measures to consider:

  1. Security Planning: The Security Summit partners have developed a comprehensive written information security plan (WISP). This 29-page document provides guidelines on safeguarding client and business information and is an invaluable resource for tax professionals.
  2. Educational Resources: Refer to IRS Publication 5293, Data Security Resource Guide for Tax Professionals, for an overview of data security best practices. IRS Publication 4557, Safeguarding Taxpayer Data, also offers detailed security recommendations. Additionally, the National Institute of Standards and Technology provides fundamentals for small business information security.
  3. Stay Updated: Subscribe to e-News for tax professionals and follow IRS social media channels for the latest updates on data security and identity theft prevention.

Conclusion

As identity theft becomes more sophisticated, tax professionals must remain vigilant and proactive. By recognizing the warning signs, implementing strong security measures, and responding swiftly to breaches, tax pros can protect their clients and their business from the damaging effects of data theft. Staying informed through the IRS, Security Summit, and other resources will help tax professionals navigate these challenges and safeguard their practice effectively.

For further information and to access helpful resources, visit the IRS identity theft information page for tax professionals.

Share this article:

Insights in Your Inbox

Join tax professionals getting practical resolution strategy, IRS updates,
and practice-scaling playbooks - about twice a month.

This field is for validation purposes and should be left unchanged.
Tax Help Jul 26, 2026

Cybersecurity Essentials for Automotive Merchants

Cybersecurity Essentials for Automotive Merchants

In the contemporary, interconnected realm where technology bolsters enterprises and individuals alike, there lurks a malevolent facet that presents considerable hazards—cyber threats. Automotive dealerships, akin to myriad other businesses, are increasingly susceptible to phishing and smishing stratagems, which can disrupt operations and compromise confidential information. The Internal Revenue Service (IRS) accentuates the necessity of remaining vigilant and enlightened to safeguard against these advancing threats.

Deciphering Phishing and Smishing

Phishing and smishing are cunning tactics employed by cybercriminals to deceive recipients into relinquishing personal or financial information or installing malicious software. These scams frequently masquerade as genuine communications from credible entities, such as the IRS or financial institutions.

Phishing generally entails fraudulent emails that purport to originate from reputable sources. These emails ensnare recipients with alarming messages or enticing offers, compelling them to click on pernicious links or divulge confidential information.

Smishing, conversely, targets victims via text messages (SMS). These messages may contain urgent alerts or fictitious claims regarding account status, accompanied by links that direct to malicious websites or prompt the download of harmful software.

The Threat Terrain for Automotive Dealerships

Recent episodes, including ransomware assaults aimed at automotive dealerships, underscore the relentless threat posed by cybercriminals. These attacks not only disrupt business operations but also imperil the security of sensitive customer data.

The IRS and its Security Summit collaborators stress the importance of proactive cybersecurity measures for businesses, particularly those in industries handling substantial financial transactions and customer information.

Paramount Practices for Cybersecurity Vigilance

  1. Educate and Train Personnel: Awareness constitutes the foremost line of defense. Train employees to identify phishing and smishing attempts, emphasizing the significance of skepticism towards unsolicited communications.
  2. Implement Robust Security Measures: Employ formidable cybersecurity solutions, such as firewalls, antivirus software, and intrusion detection systems, to thwart unauthorized access and malware.
  3. Enable Multi-Factor Authentication (MFA): Implement MFA for email and other critical systems to introduce an additional security layer against unauthorized access, even if login credentials are compromised.
  4. Verify Prior to Clicking: Foster a culture of cautious clicking. Prior to clicking on links or downloading attachments, authenticate the sender’s legitimacy through alternative communication channels.
  5. Monitor and Update Systems Regularly: Ensure software, operating systems, and applications are up-to-date with the latest security patches and updates to mitigate vulnerabilities.

Procedures to Follow if a Scam is Encountered

If you or your dealership encounters a suspicious email or text:

  • Refrain from Responding or Engaging: Avoid clicking on links, opening attachments, or providing personal information.
  • Report the Incident: Forward suspicious emails or texts to the pertinent authorities, such as [email protected], to aid in preventing further scams and protecting others.
  • Scrutinize Accounts: Regularly monitor financial accounts and credit reports for unauthorized activity, taking prompt action if dubious transactions are detected.

Conclusion

In summation, safeguarding against phishing and smishing scams necessitates perpetual vigilance, education, and proactive cybersecurity measures. By remaining informed, training employees, and implementing robust security protocols, automotive dealerships can diminish the risk of cyber threats and safeguard both their business operations and customer trust.

In the digital epoch, vigilance is paramount to staying ahead of cybercriminals. Collectively, we can cultivate a safer online environment for enterprises and individuals alike.

For further information and resources on cybersecurity best practices, visit the IRS’s Identity Protection page or consult with your IT security provider.

Stay secure, stay vigilant!


Share this article:

Insights in Your Inbox

Join tax professionals getting practical resolution strategy, IRS updates,
and practice-scaling playbooks - about twice a month.

This field is for validation purposes and should be left unchanged.
Tax Help Jul 25, 2026

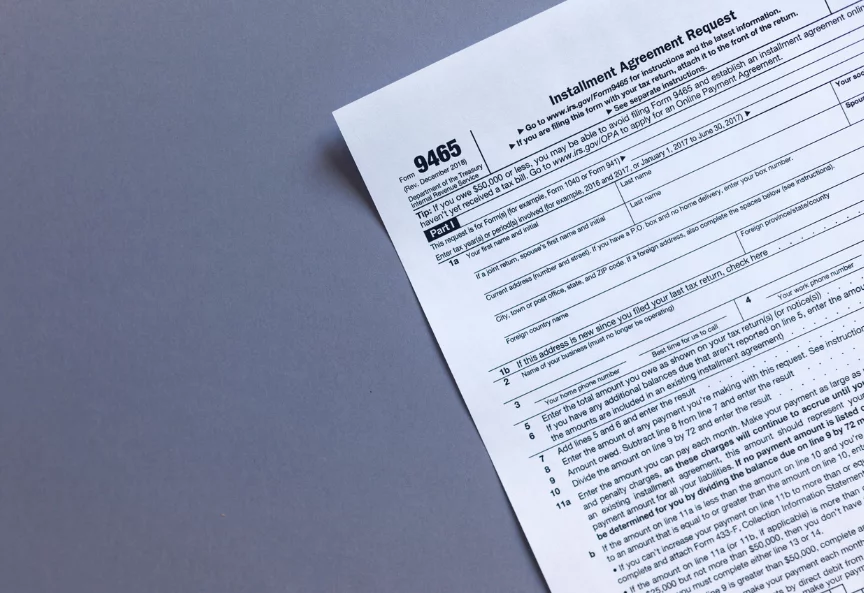
Understanding form 9465 Installment Agreement Request

Understanding form 9465 Installment Agreement Request

Each year, many Americans find themselves in a situation where they owe more income tax than they can immediately pay. For these taxpayers, the IRS offers a solution through Form 9465: Installment Agreement Request, which allows them to pay their taxes in monthly installments instead of a lump sum. It’s important to note that penalties and interest on the overdue balance will continue to accrue until the taxes are fully paid.


Key Takeaways

– Purpose of Form 9465: This form helps taxpayers who cannot pay their taxes all at once by setting up an installment plan if they meet certain conditions.

– Eligibility: Taxpayers owing $50,000 or less can often apply online, avoiding the need to file Form 9465.

– Penalties and Interest: These will continue to accrue on the overdue balance until paid off.


Who Can File Form 9465?

Taxpayers unable to pay their tax obligation in full can file Form 9465 to set up a monthly installment payment plan if they meet the following conditions:

– The taxpayer owes at most $10,000.

– They have filed all past tax returns.

– They have not entered an installment agreement in the past five years.

– They cannot pay the taxes in full when due.

– They can pay the entire outstanding balance within three years.

For those owing more than $50,000, Form 433-F, Collection Information Statement, must be submitted along with Form 9465, which cannot be done online.


Where to Get Form 9465

Form 9465 can be downloaded from the IRS website. If you owe $50,000 or less, you can use the IRS’s online payment agreement application to avoid filing the form.


Who Should Not File Form 9465?

Individuals already under an installment agreement with the IRS or those in bankruptcy who want to make an offer-in-compromise should contact the IRS directly at 1-800-829-1040 instead of filing Form 9465.


Special Considerations When Filing Form 9465

Setting up an Installment Plan

Repayments are generally required to be completed within 72 months or less. The IRS charges a one-time setup fee for installment plans, varying based on the method of payment:

– $31 for online agreements with direct debit.

– $107 for non-direct debit payments set up online.

– $130 for non-direct debit payments set up in person or by phone.

– $225 for non-online agreements and non-direct debit payments.


Low-income individuals making direct debit payments can have the $31 fee waived. Those who do not use direct debit pay a reduced cost of $43, which may be waived entirely.

If the IRS initially denies a reduced fee, taxpayers can request reconsideration by filing Form 13844, Application for Reduced User Fee for Installment Agreements.

There is an $89 fee to modify or terminate the agreement ($43 for low-income taxpayers). Interest and penalties will continue to apply to the unpaid balance.


Penalties for Unpaid Taxes

The IRS charges a daily compounding interest rate equal to the short-term federal funds rate plus 3%, calculated quarterly. A failure-to-pay penalty of 0.5% on the unpaid balance each month (up to 25%) applies. The penalty is reduced to 0.25% per month for those on an installment plan.

Penalties and interest can add up to 9% to 12% per year, so paying more than the minimum monthly payment whenever possible is advisable.


Example of Penalties

Consider Fred, who filed his 2022 taxes in April 2023 and owes $7,000. He submits Form 9465 and establishes a 36-month installment plan. If the federal funds rate is 3%, the IRS will charge Fred 6% interest on the balance. With a 0.5% failure-to-pay penalty, Fred faces another 6% annually in penalties until the balance is paid off. This totals 12% of $7,000 annually, although the amount decreases as he repays the principal.


Methods of Payment

Taxpayers can pay via personal checks, cashier’s checks, money orders, direct debit, credit card, or the Electronic Federal Tax Payment System (EFTPS). Payments must be made by the specified date each month. Those mailing payments should be made at least seven to ten business days before the due date to ensure timely receipt.

The IRS website lets taxpayers modify their installment agreements online, including payment dates and terms. Authorized representatives can also access the site to make changes on behalf of their clients.


Benefits of Installment Plans

The primary benefit of an installment plan is that it gives taxpayers more time to pay off their federal taxes in an orderly manner. If the terms of the agreement are honored, the IRS or private collection agencies will cease collection efforts.


Additional Information

Eligible individuals can receive a six-month extension for filing their tax returns and possibly paying their tax bills under certain financial hardships.


How to Set Up a Payment Plan with the IRS

To set up an installment payment plan, you can apply online through the IRS Online Payment Agreement tool or by phone or mail by submitting Form 9465.


Interest and Penalties on Payment Plans

A short-term payment plan is typically free of charge. Long-term payment plans have varying setup fees depending on the payment method. These fees are reduced for low-income earners. Note that accrued penalties also need to be paid.


Electronic Filing

Form 9465 can be filed electronically if the amount owed is less than $50,000.


Difference Between Forms 9465 and 433-F

Form 433-F details how much interest and penalties are owed, while Form 9465 establishes an installment plan to pay those fees. Taxpayers owing more than $50,000 must submit both forms.


The Bottom Line

Taxpayers with outstanding tax bills don’t have to panic. The installment agreement application process is relatively quick and painless. However, penalties and interest will add up over time. Making arrangements upfront is better to avoid further complications and additional charges.


You can access Form 9465 from the IRS website or by calling 1-800-829-1040.

Share this article:

Insights in Your Inbox

Join tax professionals getting practical resolution strategy, IRS updates,
and practice-scaling playbooks - about twice a month.

This field is for validation purposes and should be left unchanged.